Market updates
Weekly Rate Tracker 10/28/2026
Weekly Rate Tracker: Mortgage Rates Ease Again, but Inflation Keeps Markets on Edge
 Frank EllerbroekMortgage Broker · NMLS #128726Vantage Mortgage Brokers · NMLS #35986Published 2 min read
Accessibility
Market updates
Weekly Rate Tracker: Mortgage Rates Ease Again, but Inflation Keeps Markets on Edge
Frank EllerbroekMortgage Broker · NMLS #128726Vantage Mortgage Brokers · NMLS #35986Published 2 min read
🏡 Weekly Rate Tracker | October 28, 2026
Mortgage rates eased for the second consecutive week—a little breathing room after several weeks of increases.
The latest Mortgage Bankers Association survey showed:
📉 Average 30-year fixed conforming rate: 7.37%, down from 7.41%
📈 Mortgage applications: Up 3.4%
🏠 Purchase applications: Up 4%
🔄 Refinance applications: Up 3%
Despite the improvement, rates remain more than a full percentage point higher than this time last year. These are national survey averages with points and fees, rather than a personalized rate quote.
The Fed held its benchmark rate steady today, but that doesn’t mean mortgage rates will stand still. Mortgage pricing follows the bond market, where inflation expectations, economic data, and Fed commentary can quickly change the outlook.
Oil-price volatility and geopolitical tensions remain key concerns. Investors are also watching upcoming inflation data and next week’s midterm elections. Once the results are confirmed, we’ll see how markets respond—there’s no guaranteed direction for rates.
For buyers, even a modest improvement makes it worth refreshing the numbers, including whether seller credits toward closing costs or a rate buydown could help. For homeowners, refinancing should come down to savings, costs, and the time needed to break even.
I compare multiple wholesale lenders to help you understand your options as pricing changes.
MONTHLY PAYMENTS: This reflects Principal and Interest (P&I) on Conventional and also including PMI on FHA. Taxes and insurance not included, but need to be factored in housing payments and budget as these can vary by property. A VMG Mortgage Broker can run an analysis anytime by request.
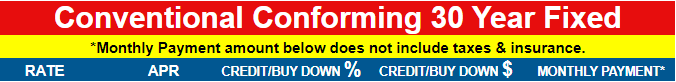
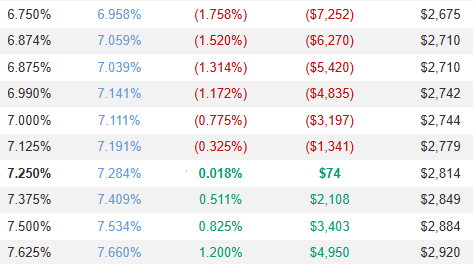
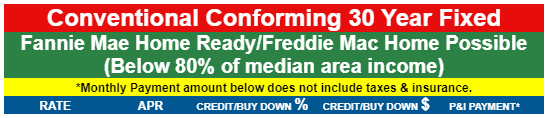
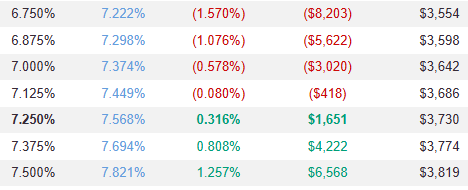
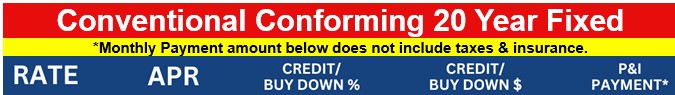
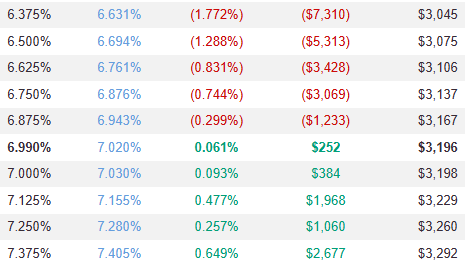
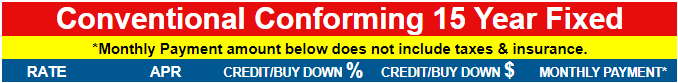
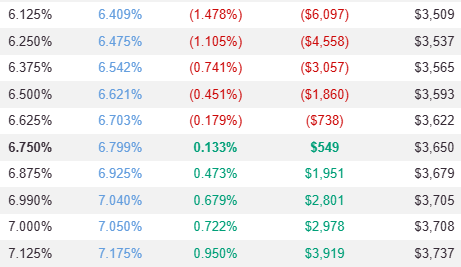
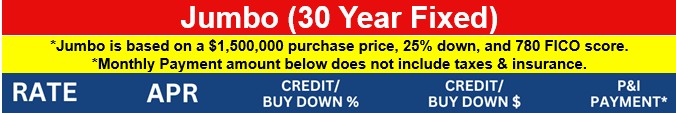
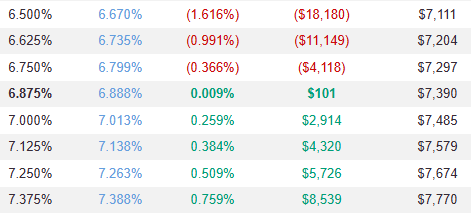
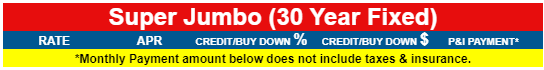
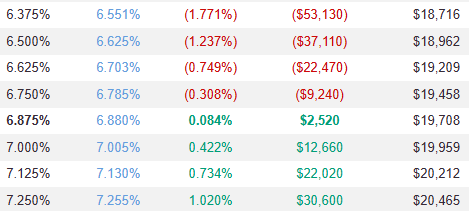
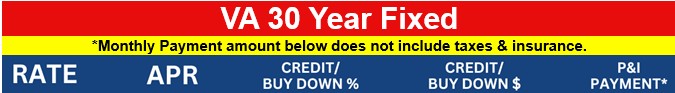
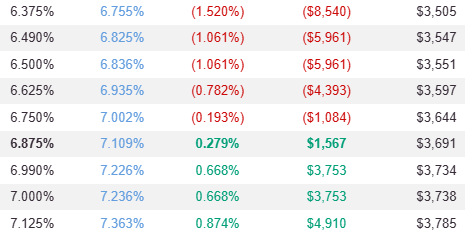
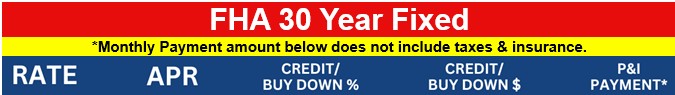
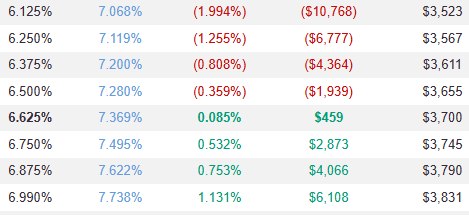
*Rates are subject to change. Conforming conventional interest rate samples based on a $550,000 purchase price, $412,500 loan amount, 25% down, 740 FICO score, with impounds on a 30-day rate lock period and $1150 underwriting fee if not covered by lender rebates. FHA is based on a $550,000 purchase price, $530,750 base loan amount and a 3.5% down payment, but other same variables. This pricing engine reflects the most favorable results after comparing our network of wholesale lending partners. This pricing engine does not include any other applicable 3rd party title and escrow charges, appraisal, credit report, or prepaid tax and insurance reserves. The displayed annual percentage rates (APRs) include total points and additional prepaid finance charges but do not include other closing costs. Loan pricing may only be locked through a VMB home loan consultant to be effective after a formal loan application. Rates will depend in part on your unique credit history and transaction characteristics. Monthly payments include principal, interest, and PMI if applicable, but do not taxes and insurance. This is not a formal Loan Estimate (LE). A Loan Estimate is provided and can be requested pursuant to Federal regulations and with a formal loan application. This information does not constitute a loan commitment or approval.
Tell Frank what you’re trying to do. He’ll shop 35+ wholesale lenders and show you the options side by side.
This article is general information, not a Loan Estimate, a commitment to lend or financial advice for your specific situation. Rates and programs change; confirm the details with Frank before you act. Frank Ellerbroek, NMLS #128726, Vantage Mortgage Brokers, NMLS #35986.
Market updates2 min read
Market updates3 min read